
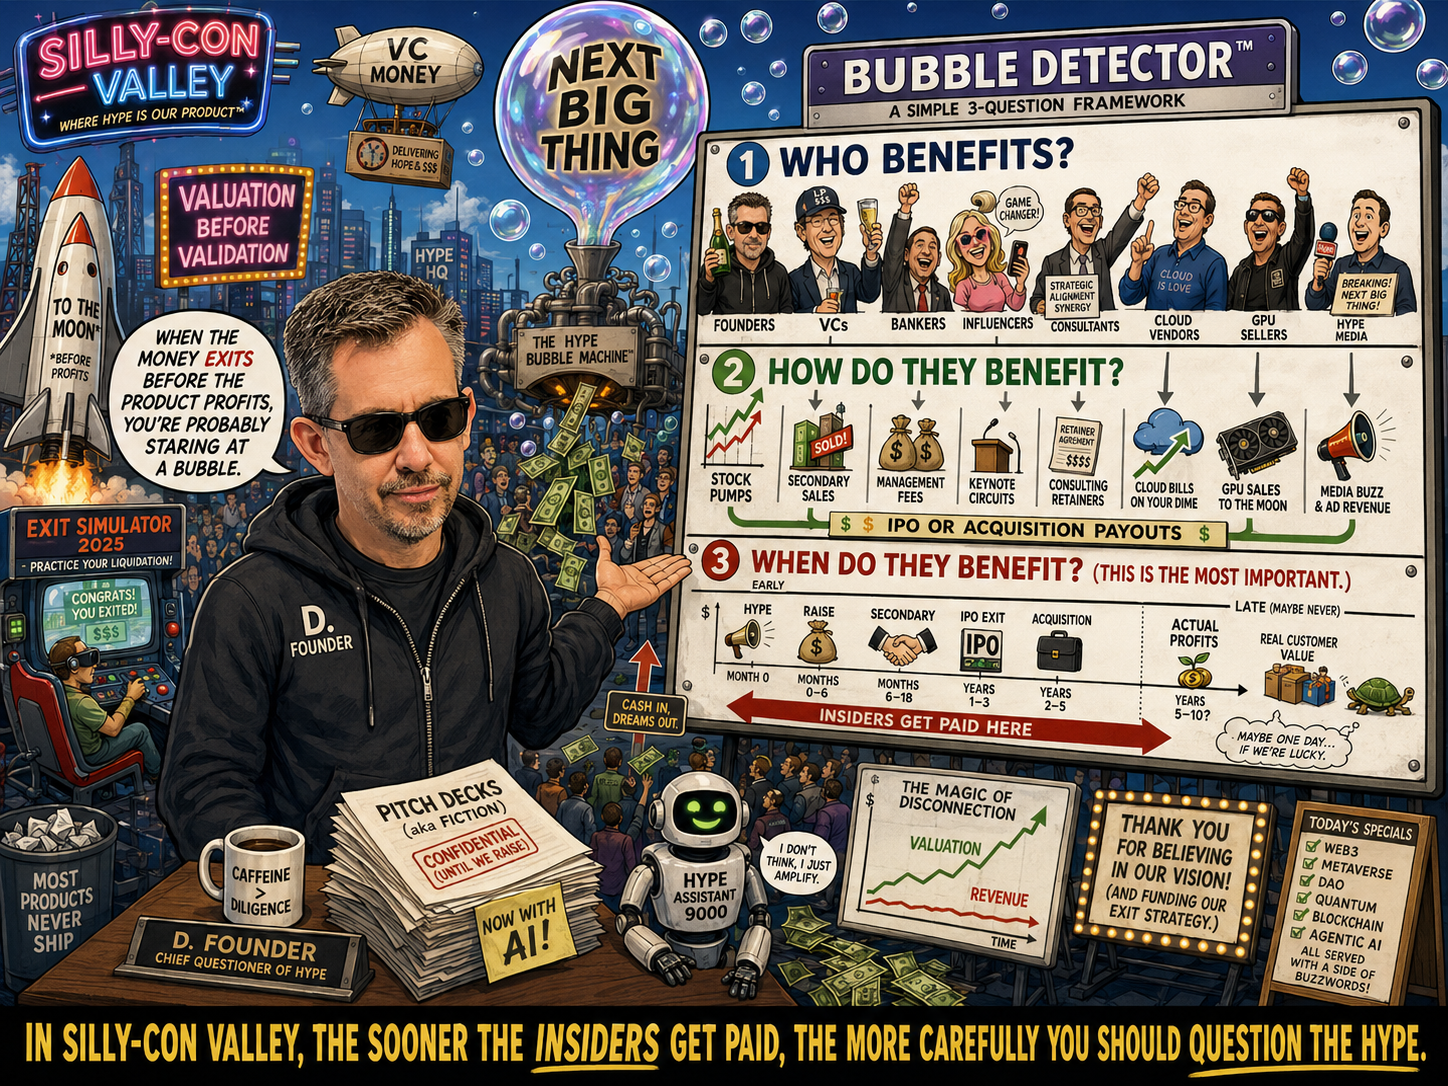
Why technological revolutions can make investors rich without improving society.
Every speculative frenzy begins with the same opening act.
A new technology arrives.
Capital floods in.
Founders discover adjectives.
Investors discover religion.
Everything is transformative, exponential, inevitable, and—according to the pitch deck—already disrupting a $14 trillion market.
Then comes the inevitable question.
Is this a bubble?
The usual answers involve valuations, revenue multiples, IPOs, and whether a startup with twelve employees and a chatbot should really be worth more than a regional airline.
But perhaps we're asking the wrong question.
Instead of asking whether a technology will create enormous wealth, we should be asking:
Who will actually get rich? And who will actually benefit?
Because creating wealth and creating prosperity are not the same thing.
A speculative bubble can create spectacular fortunes for founders, venture capitalists, bankers, and whoever managed to sell before everyone noticed the PowerPoint was doing most of the work.
A genuine technological transformation can do something much more significant.
It can improve life for people who never invested a dollar.
Workers. Customers. Suppliers. Small businesses. Entire communities.
A bubble creates fortunes.
A boom creates prosperity.
And while the economic distinction is more complicated, the distinction between financial success and societal progress shouldn't be.
Unfortunately, Silicon Valley has become exceptionally good at confusing the two.
Bubbles Are Extremely Good at Creating Wealth
Just not necessarily for you.
One reason speculative bubbles are difficult to recognize from inside them is that they genuinely create wealth.
At least on paper.
A startup raises funding at a $4 billion valuation.
Its founders become extraordinarily wealthy on paper. Early investors mark up their portfolios. Employees calculate the theoretical value of their options.
Another venture fund raises a larger fund because its previous fund invested in the company whose valuation the venture funds helped increase.
Everyone congratulates everyone else for creating value.
Sometimes a product has even been involved.
The problem is that rising asset prices are not the same thing as rising societal value.
If ten investors repeatedly trade a company's shares at higher valuations, the economy has not necessarily become ten times more productive.
The spreadsheet has.
This is the magic trick at the center of many speculative bubbles: financial value becomes confused with societal value.
People treat a higher valuation as evidence that something important has happened.
Sometimes something important has happened.
Sometimes three venture firms have simply agreed that something important will probably happen later.
Preferably before the next funding round.
And here's the clever part.
The valuation doesn't just measure the narrative.
It reinforces it.
Higher valuations attract more capital. More capital attracts talent, media attention, and customers. That attention helps justify even higher valuations.
Eventually, the market begins treating the price of the promise as proof that the promise is being fulfilled.
Funding becomes validation. Valuation becomes achievement. Speculation becomes progress.
Welcome to the innovation economy.
Where the future is always worth more than the present, particularly when someone else is financing it.
A Real Boom Leaks
The most socially consequential characteristic of a genuine technological boom is that its benefits become difficult to contain.
Productivity rises.
Products become cheaper or better.
New businesses emerge.
Entire industries become more efficient.
New opportunities appear for people who had nothing to do with inventing or financing the original technology.
Consider electricity.
The greatest achievement of electrification wasn't that a handful of electrical companies became enormously valuable.
It was that electricity transformed factories, homes, transportation, communication, entertainment, and everyday life.
The same was true of computing, telecommunications, and the internet.
Enormous fortunes were created.
But the technologies also became infrastructure.
Millions of people who never owned shares in Intel, Microsoft, Cisco, or Apple benefited from cheaper computing, better communications, new businesses, and previously unimaginable opportunities.
Not everyone benefited equally.
Some workers and industries were displaced. New monopolies emerged. Wealth and power became concentrated in new places.
Technological progress has never guaranteed equitable outcomes.
But its benefits extended far beyond the original investors.
That's the distinction worth paying attention to.
A financial boom makes assets more valuable.
A technological boom makes new capabilities possible.
Societal progress happens when those capabilities translate into better lives.
The three often overlap.
But they are not interchangeable.
Follow the Surplus
Here's a question Silicon Valley rarely puts on the opening slide of its pitch decks:
Where does the value go?
Imagine a new technology increases productivity by 30%.
Fantastic.
Now, who gets the 30%?
Do workers earn more?
Do customers pay less?
Do businesses reinvest the savings?
Does society get better services, more leisure, or greater economic security?
Or does most of the gain flow to shareholders while everyone else receives an inspirational email about doing more with less?
The technology may be equally impressive in both scenarios.
The social outcome is very different.
And that difference isn't a technical question.
It's economic and political.
Technology determines what becomes possible.
Markets, institutions, competition, ownership, and policy help determine who benefits.
Yet the technology industry has developed a remarkably convenient habit of treating the second question as if the first automatically answers it.
Build something revolutionary.
Create enormous shareholder value.
Assume society will figure out the rest.
Which brings us to Silicon Valley's favorite word.
Democratization.
Everyone wants to democratize something.
Knowledge. Creativity. Finance. Transportation. Education. Intelligence.
Access gets democratized.
Ownership remains surprisingly artisanal.
And when the promised productivity gains arrive, the industry's definition of democratization sometimes undergoes an unexpected refinement.
The benefits belong to everyone.
The profits belong to the shareholders.
Terms and conditions apply.
What If the System Is Working Exactly as Designed?
It's tempting to describe the concentration of technological wealth as a failure of distribution.
But that assumes broad distribution was the intended outcome.
Venture capital funds are designed to generate returns for investors.
Public companies face powerful incentives to maximize shareholder value.
Executives are frequently rewarded through compensation tied to stock performance.
None of these structures automatically rewards a company for making its workers more economically secure, reducing inequality, or ensuring society receives a fair share of productivity gains.
Those outcomes may happen.
But they are not guaranteed.
And this is where the usual technology narrative becomes interesting.
We are told that innovation will make everyone better off.
Yet the institutions financing and commercializing that innovation are primarily rewarded for how much financial value they can capture.
There's nothing inherently wrong with investors earning returns for taking risks.
The question is whether private financial returns have become our default measure of public progress.
Because if the scoreboard only measures shareholder wealth, we shouldn't be surprised when everyone plays to maximize shareholder wealth.
Perhaps the distribution problem isn't a bug.
Perhaps it's a feature.
And unlike most Silicon Valley features, this one appears to be working exactly as specified.
The Bubble Can Contain a Real Technology
An important distinction often gets lost in these debates.
Calling something a bubble doesn't mean the underlying technology is useless.
The dot-com bubble was a bubble.
The internet was real.
Railroad speculation produced enormous financial bubbles.
Railroads also transformed economies.
A speculative bubble can form around a genuine technological revolution because markets are quite good at recognizing that something important is happening.
They're considerably less disciplined at estimating exactly how important it will be.
Investors discover a powerful technology and immediately begin pricing every company as though it will personally conquer civilization.
It's like discovering oil and concluding that every gas station should be worth $400 billion.
Eventually, reality introduces itself.
Many companies disappear.
A few survive.
Some infrastructure remains.
And sometimes, after the financial bubble bursts, the actual economic boom continues—or even accelerates.
This distinction matters because the people who profit from the speculative phase and the people who benefit from the productive phase are not necessarily the same.
The technology can succeed even when the investment thesis fails.
And the investment thesis can succeed without delivering the promised societal transformation.
Which brings us to AI.
The AI Question Nobody Wants on the Pitch Deck
Artificial intelligence makes this distinction particularly important.
There is genuine technological progress happening.
The question isn't simply whether AI is real or useful.
It is.
Nor is it whether AI could generate enormous economic value.
It could.
The more consequential question is:
What happens to the gains?
Suppose AI dramatically increases productivity.
Companies automate substantial portions of their operations.
Profits increase.
Stock prices rise.
Entire categories of work become cheaper to perform.
Now suppose most of the resulting wealth flows to semiconductor manufacturers, cloud providers, model owners, and investors.
Meanwhile, wages stagnate, employment becomes less secure, and workers are expected to produce twice as much for the same compensation.
What have we achieved?
From the perspective of the capital markets, perhaps the greatest technological revolution in history.
From the perspective of the average worker, a particularly elaborate restructuring exercise.
GDP could rise.
Market capitalization could soar.
Executive compensation could reach levels previously associated with minor European monarchies.
And millions of people could still ask:
"Wasn't this supposed to make life better?"
That is the distribution problem hiding underneath the AI debate.
We spend enormous amounts of time arguing about what AI can do.
Far less time discussing who will own those capabilities, who will control their deployment, and who will capture the resulting economic value.
Yet those questions may ultimately determine whether AI becomes a broad engine of prosperity or another extraordinary mechanism for concentrating wealth and power.
The industry keeps promising abundance.
But abundance for whom?
A world in which everything becomes cheaper to produce but increasingly expensive to access isn't necessarily progress.
It may simply be a more efficient system of extraction.
Now with AI.
Society Does Not Live on Market Cap
Silicon Valley has developed an unfortunate habit of treating company valuation as a scoreboard for human progress.
A trillion-dollar company is presented almost automatically as evidence that something wonderful has happened.
Sometimes it has.
But society cannot spend market capitalization.
People experience technological progress through considerably more ordinary things.
Higher wages.
Lower prices.
Better services.
More leisure.
Improved healthcare.
Safer working conditions.
Greater opportunity.
More economic security.
These outcomes are neither automatic nor guaranteed by innovation.
They depend on how the benefits are distributed.
If a technological revolution produces spectacular returns for capital while everyone else receives a subscription fee and a layoff announcement, something has gone wrong in the distribution layer.
Maybe the technology succeeded.
Maybe the business model succeeded.
Maybe the investors succeeded.
But calling the entire thing a societal triumph feels generous.
After all, making the richest people in the world even richer is not an especially ambitious definition of progress.
We've already demonstrated considerable competence in that area.
The Ultimate Test
History will not judge today's technological revolutions solely by how many billionaires they created.
Silicon Valley already has excellent billionaire throughput.
The more meaningful question is whether these technologies eventually improve life for people who never bought the stock, joined the startup, attended the conference, or even knew what a Series C was.
Because a technology doesn't become socially transformative merely because it creates enormous financial value.
It becomes transformative when that value translates into meaningful improvements in people's lives.
Innovation creates possibilities.
Business models determine how those possibilities become products.
Society determines—or fails to determine—how it shares the resulting prosperity.
We should stop confusing success at one level with success at all three.
A bubble can make investors rich by convincing them the future will be valuable.
A technological boom can make that future possible.
But societal progress requires something more.
It requires making that future better for people who don't own a piece of it.
And perhaps that's the question we should be asking about AI, and every technological revolution that follows:
Are we building a better future for society, or just a more valuable future for shareholders?
Welcome to Silly-con Valley. Where prosperity is democratized immediately after the preferred shareholders get paid.